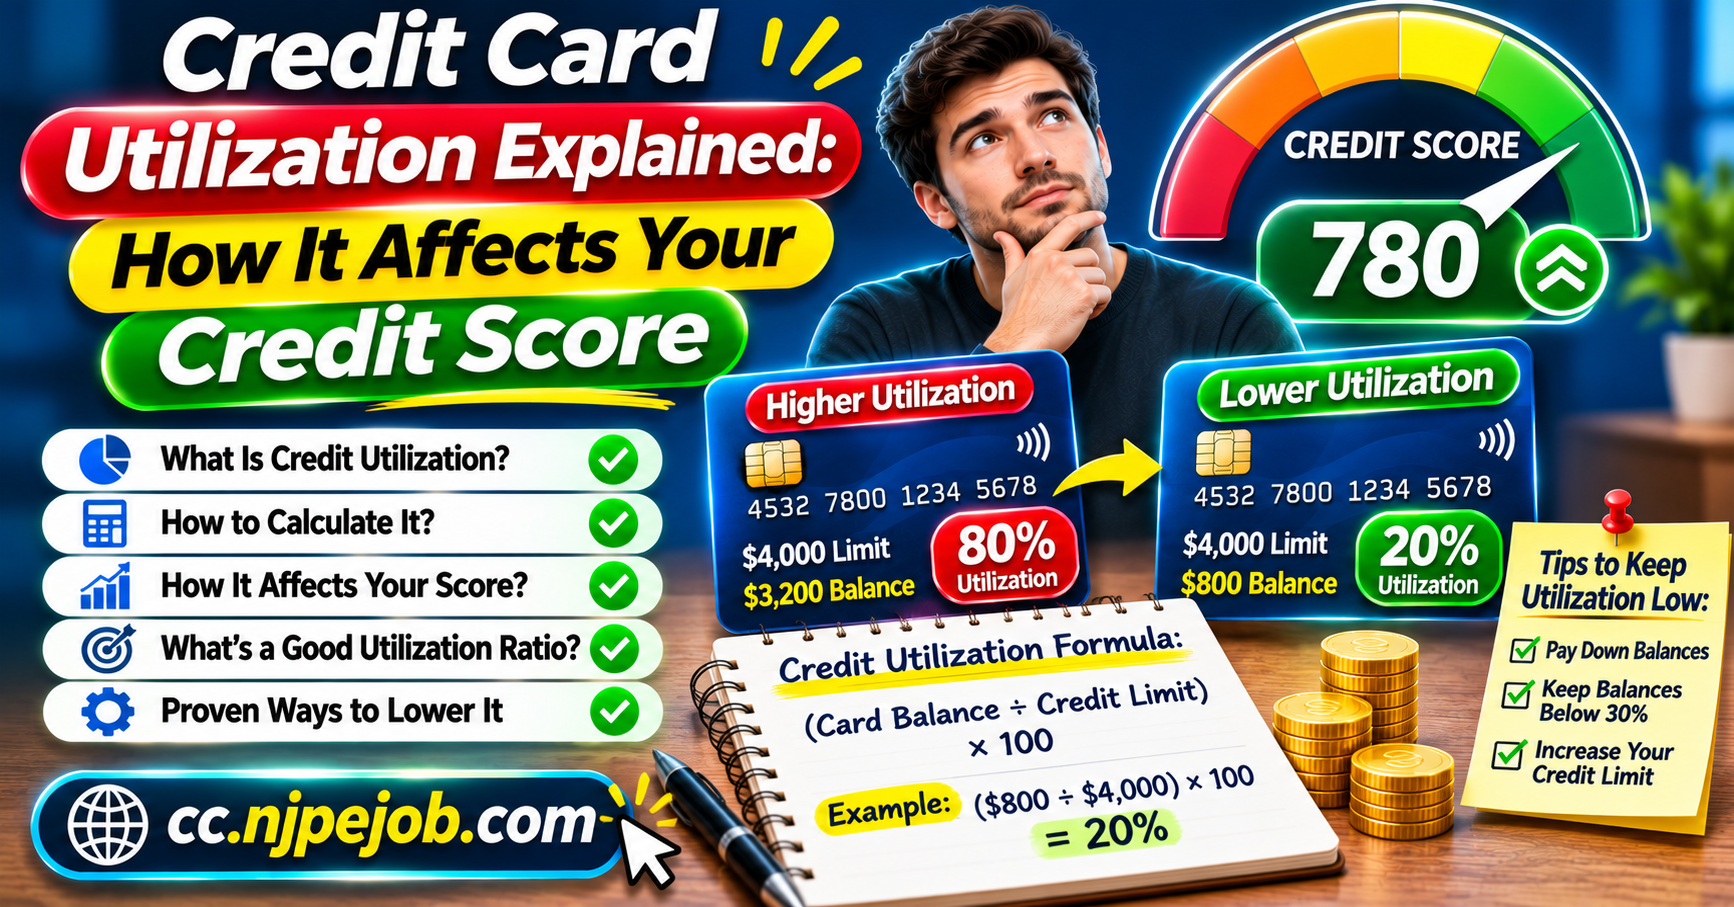
Credit Card Utilization Explained: How It Affects Your Credit Score
Understanding how credit cards affect your credit score is an important part of managing personal finances. While many consumers focus on making payments on time, another factor can significantly influence their creditworthiness: credit card utilization.
Credit utilization measures how much of your available credit you are using at a particular time. It helps lenders and credit scoring systems evaluate how responsibly you manage revolving credit accounts.
A high utilization ratio may suggest that you are relying heavily on borrowed money, while a lower ratio can indicate that you have more available credit and are managing your balances carefully.
The good news is that credit utilization is one of the credit scoring factors you may be able to improve relatively quickly.
In this guide, we explain what credit card utilization means, how to calculate it, how it affects your credit score, and practical strategies to manage it effectively in 2026.
What Is Credit Card Utilization?
Credit card utilization, also called the credit utilization ratio, represents the percentage of your available revolving credit that you are currently using.
For example, imagine that you have a credit card with a $5,000 credit limit.
If your outstanding balance is $1,000, you are using 20% of your available credit.
This means your credit utilization ratio is 20%.
Credit scoring systems consider this information because it provides insight into your borrowing behavior.
Using a large percentage of your available credit may indicate financial pressure, even if you consistently make your payments on time.
On the other hand, keeping balances relatively low can demonstrate that you are not relying excessively on credit.
Credit utilization is primarily associated with revolving credit accounts, such as credit cards.
Installment loans, including many auto loans and personal loans, are evaluated differently.
How to Calculate Your Credit Utilization Ratio
Calculating credit utilization is straightforward.
Use the following formula:
Credit Utilization Ratio = (Credit Card Balance ÷ Credit Limit) × 100
Consider the following example.
Suppose your credit card has:
Credit limit: $4,000
Outstanding balance: $1,200
Your calculation would be:
($1,200 ÷ $4,000) × 100 = 30%
Your credit utilization ratio is 30%.
Now imagine you reduce your balance to $400 while keeping the same credit limit.
The new calculation becomes:
($400 ÷ $4,000) × 100 = 10%
Your utilization has decreased from 30% to 10%.
This reduction may positively influence your credit score when the updated balance is reported to credit bureaus.
However, the exact score change depends on your complete credit profile and the scoring model used.
How to Calculate Utilization Across Multiple Credit Cards
If you have several credit cards, calculating your overall utilization requires combining the reported balances and credit limits.
For example:
| Credit Card | Credit Limit | Balance |
|---|---|---|
| Card A | $3,000 | $600 |
| Card B | $5,000 | $1,000 |
| Card C | $2,000 | $400 |
| Total | $10,000 | $2,000 |
Your overall credit utilization would be:
($2,000 ÷ $10,000) × 100 = 20%
This means you are using 20% of your total available credit.
However, credit scoring systems may also consider the utilization of individual cards.
For this reason, maintaining reasonable balances across your accounts can be more beneficial than focusing only on the combined percentage.
How Does Credit Utilization Affect Your Credit Score?
Credit utilization is an important part of several widely used credit scoring models, including FICO and VantageScore.
FICO scores consider credit utilization within a broader category called "Amounts Owed."
This category generally accounts for approximately 30% of a typical FICO score.
However, it is important to understand that credit utilization alone does not represent the entire 30%.
Other factors, including outstanding debt and the number of accounts carrying balances, are also considered.
Credit scoring systems use utilization to assess how much revolving credit you are using compared with your available limits.
High utilization can indicate greater borrowing risk.
Lower utilization generally supports healthier credit scoring outcomes.
Your payment history, length of credit history, credit mix, and new credit activity also influence your overall score.
Therefore, lowering utilization may help your score, but it does not guarantee a specific increase.
What Is a Good Credit Utilization Ratio?
Financial educators frequently recommend keeping credit utilization below 30%.
This is a useful general guideline, but it is not a strict threshold that guarantees a good credit score.
Credit scoring systems can distinguish between different utilization levels below 30%.
For example, someone using 8% of available credit may receive a more favorable utilization assessment than someone using 28%, depending on other information in their credit report.
Consumers with excellent credit scores often maintain utilization below 10%.
However, you should not assume that reaching a particular percentage will automatically produce a specific credit score.
The most practical approach is to keep your utilization as low as reasonably possible while maintaining responsible payment habits.
Remember that you do not need to carry interest-bearing debt to build credit.
Why High Credit Utilization Can Hurt Your Score
High credit utilization can suggest that you are approaching your borrowing limits.
For example, suppose two consumers each have a credit limit of $5,000.
Consumer A has an outstanding balance of $500.
Consumer B has an outstanding balance of $4,500.
Consumer A is using 10% of available credit, while Consumer B is using 90%.
Even if both consumers make their minimum payments on time, Consumer B's high utilization may negatively affect their credit score.
Credit scoring models consider high revolving balances relevant because they may indicate greater financial risk.
Additionally, carrying large balances can create significant interest expenses.
Reducing unnecessary credit card debt can therefore support both your financial health and your credit profile.
Does Credit Utilization Matter on Individual Cards?
Yes. Both overall utilization and individual card utilization can matter.
Imagine you have two credit cards.
The first has a $1,000 limit with a $900 balance.
The second has a $9,000 limit with no balance.
Your total utilization is only 9%.
However, your first credit card has a utilization rate of 90%.
Depending on the scoring model, that heavily utilized individual card may still influence your credit score.
This is why spreading balances responsibly or paying down heavily utilized accounts can sometimes improve your credit profile.
However, transferring balances should only be considered after reviewing any applicable fees, interest rates, and promotional conditions.
When Do Credit Card Companies Report Utilization?
Credit card issuers commonly report account information to credit bureaus around the time monthly billing statements are generated.
However, reporting schedules vary by issuer.
The balance reported to the credit bureaus may not match the balance currently displayed in your banking application.
For example, suppose your statement closes on the 15th of each month.
If your balance is $2,000 on that date, the issuer may report that amount even if you pay it in full a few days later.
Your credit report could temporarily show relatively high utilization.
This does not mean you have failed to pay your bill.
It simply reflects the balance reported at a particular time.
Understanding reporting dates can help you manage utilization more effectively.
1. Pay Down Existing Credit Card Balances
One of the simplest ways to reduce utilization is to lower your outstanding credit card debt.
Consider a card with a $5,000 limit and a $3,000 balance.
Its utilization ratio is 60%.
If you pay down the balance to $1,000, utilization falls to 20%.
Reducing debt can improve your available credit and lower future interest costs.
If you have multiple credit cards, consider prioritizing balances with high interest rates.
Continue making all required minimum payments while directing available extra funds toward your repayment strategy.
Avoid using emergency savings for large repayments without considering your overall financial stability.
2. Make Payments Before Your Statement Closing Date
Many consumers pay their credit card bills by the due date, which is essential for avoiding late payments.
However, paying part of your balance before the statement closing date may help reduce the amount reported to credit bureaus.
For example, imagine your credit limit is $2,000 and your outstanding balance is $1,000.
If you pay $800 before the reporting date, your remaining balance becomes $200.
Your utilization decreases from 50% to 10%.
If the issuer reports the lower balance, your credit report may reflect the improvement.
This strategy does not replace making required payments on time.
You should still pay your statement balance in full by the due date whenever financially possible.
3. Consider Requesting a Credit Limit Increase
Increasing your available credit can reduce utilization without requiring you to close an account.
For example:
Current credit limit: $3,000
Current balance: $900
Current utilization: 30%
If your issuer increases your credit limit to $6,000 while the balance remains $900, your utilization drops to 15%.
However, a credit limit increase is not guaranteed.
The issuer may review your income, payment history, and credit profile.
Some requests can also result in a hard credit inquiry, depending on the financial institution.
Before requesting an increase, ask whether the issuer will perform a hard or soft inquiry.
Most importantly, avoid increasing your spending simply because you have received a larger credit limit.
4. Avoid Closing Credit Cards Without a Reason
Closing a credit card can reduce your total available credit.
This may increase your utilization ratio if you still have balances on other cards.
For example, suppose you have two credit cards with a combined credit limit of $10,000 and an outstanding balance of $2,000.
Your utilization is 20%.
If you close a card with a $5,000 limit while your remaining balance stays at $2,000, your utilization could increase to 40%.
That increase may negatively affect your credit score.
However, keeping every credit card open is not always the best decision.
Closing an account may be reasonable if it has expensive annual fees, poor terms, or creates a risk of overspending.
Consider both the financial costs and credit implications before making a decision.
5. Avoid Unnecessary Credit Card Spending
A larger credit limit does not mean you have additional income.
One of the easiest ways to maintain low utilization is to use your credit card only for purchases you can comfortably repay.
Consider using a monthly budget to track expenses.
Separate essential spending from discretionary purchases and review your account balance regularly.
Credit card alerts can notify you when spending approaches a chosen amount.
Maintaining a manageable balance can help prevent financial stress and reduce unnecessary interest charges.
6. Review Your Credit Reports Regularly
Your credit utilization calculations depend on the balances and limits reported by lenders.
If your credit report contains an incorrect balance or credit limit, your reported utilization may be inaccurate.
In the United States, consumers can review their credit reports from Equifax, Experian, and TransUnion.
Check for unfamiliar accounts, incorrect credit limits, and balances that do not match your records after allowing for normal reporting delays.
If you find inaccurate information, follow the appropriate credit reporting dispute process.
Regular monitoring can also help identify possible identity theft or unauthorized credit activity.
Does Paying Your Credit Card in Full Help Your Credit Score?
Paying your credit card statement balance in full is generally an excellent financial habit.
It can help you avoid purchase interest when your account qualifies for a grace period.
However, your reported utilization depends on when the issuer sends balance information to credit bureaus.
You might pay every statement in full while your credit report temporarily displays a balance.
That is normal.
Paying before a statement closes may lower your reported utilization, but it is not always necessary for maintaining good credit.
The most important priorities remain paying on time, avoiding excessive debt, and managing your credit responsibly.
Can You Have Too Little Credit Utilization?
A very low utilization ratio is generally favorable.
However, some credit scoring models may treat a small reported balance differently from having every revolving account report a zero balance.
This does not mean you should intentionally carry debt or pay interest.
For example, you can use a credit card for a small purchase, allow an affordable balance to appear on your statement, and pay the statement in full by its due date.
That can demonstrate account activity without creating an ongoing interest-bearing balance, assuming your purchase grace period applies.
Avoid borrowing unnecessarily just to achieve a particular utilization percentage.
How Quickly Can Lower Utilization Improve Your Score?
Credit utilization can sometimes affect credit scores relatively quickly.
Many widely used scoring models focus primarily on the most recently reported balances.
If you pay down a large balance and the issuer reports the updated information, your score may improve during a subsequent credit reporting cycle.
However, not every scoring model treats historical utilization the same way.
Newer models, including FICO 10 T and VantageScore 4.0, can consider trends in credit behavior over time.
Therefore, maintaining healthy utilization consistently is preferable to temporarily reducing balances only before applying for credit.
Your actual score change also depends on the rest of your credit history.
Frequently Asked Questions
Is 30% credit utilization good?
Keeping utilization below 30% is a common guideline, but it is not a guaranteed scoring threshold. Lower percentages can be more favorable, depending on your credit profile.
Does 0% utilization hurt your credit score?
Some scoring models may award slightly different results when every revolving account reports zero compared with a small positive balance. However, you should never carry interest-bearing debt solely to improve a score.
Does high credit utilization affect your score immediately?
Your score may be affected after the higher balance is reported to credit bureaus. Reporting dates vary by credit card issuer.
Can requesting a credit limit increase improve utilization?
Yes. A higher credit limit can reduce your utilization if your outstanding balance stays the same. However, approval is not guaranteed, and the request may involve a credit inquiry.
Is credit utilization more important than payment history?
Payment history generally has a greater weight in typical FICO scoring models. However, utilization remains an important factor that can influence your overall credit score.
Final Thoughts
Credit card utilization is an important part of understanding how revolving credit affects your financial reputation.
A lower utilization ratio generally indicates that you are using a smaller portion of your available credit.
While keeping utilization below 30% is a useful starting guideline, maintaining even lower balances may provide additional credit scoring benefits.
The most effective strategies include paying down outstanding debt, monitoring statement balances, making timely payments, and avoiding unnecessary spending.
If appropriate, requesting a credit limit increase or keeping useful existing accounts open may also help manage utilization.
Remember that a strong credit score develops through several responsible financial habits, not one percentage alone.
By understanding how credit utilization works and managing your credit cards carefully, you can build a healthier credit profile and make more informed borrowing decisions.
Disclaimer: This article provides general financial education and does not constitute personalized financial advice. Credit scoring results vary depending on the scoring model, credit bureau information, and individual financial circumstances.